Britain's Gambling Market Shows Modest Expansion Amid Sector Shifts
Written by Zoe Foster · Sep 23, 2026
Britain's Gambling Market Shows Modest Expansion Amid Sector Shifts
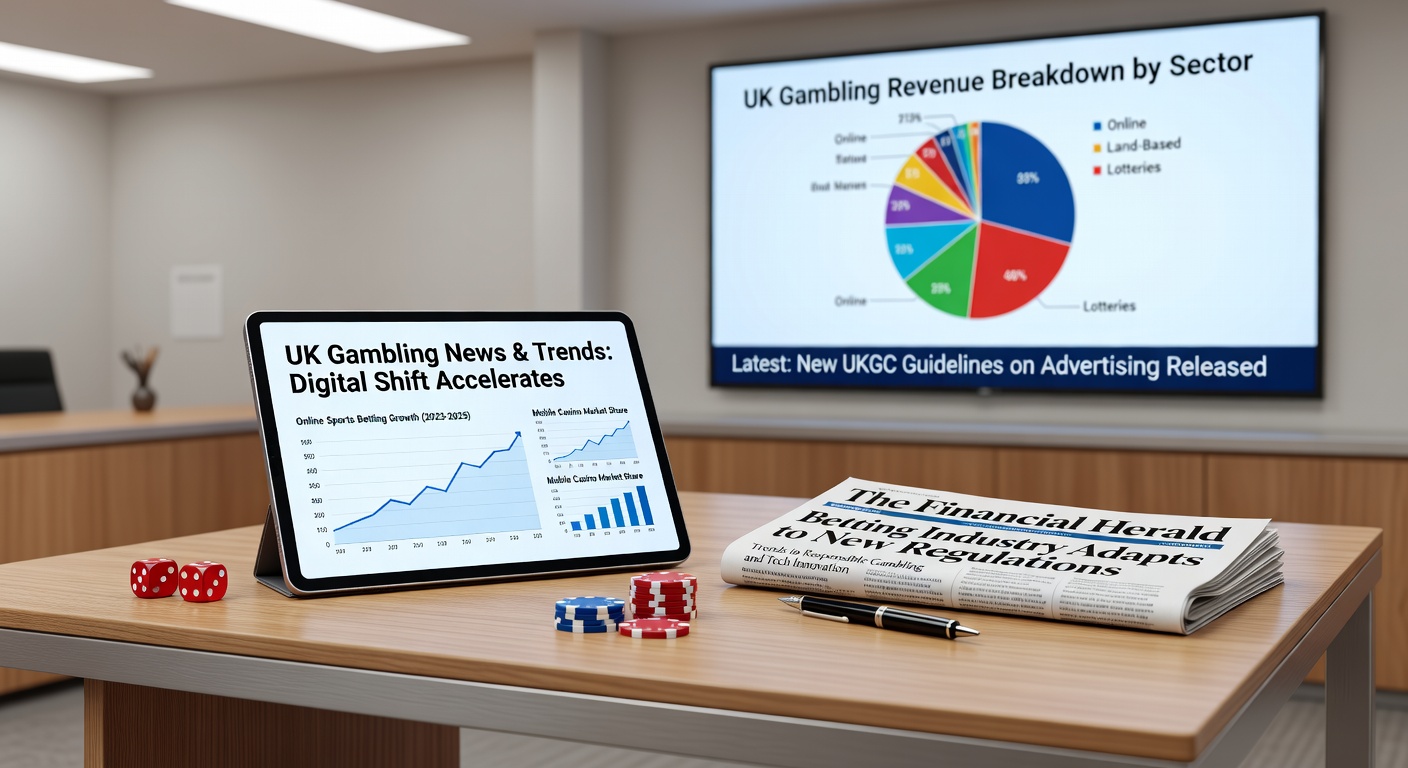
Data from the latest financial year reveals Great Britain's customer-facing gambling industry reached £17.5 billion in gross gambling yield, marking a 4.4 percent rise compared with the prior period, while the figure climbs to £13.2 billion when lotteries receive exclusion and the growth rate adjusts to 4.7 percent. The remote sector led this expansion with a 6.9 percent increase that brought online contributions to £8.3 billion, and within that channel the casino and slots segments accounted for the largest share of new activity. Land-based operations recorded a more restrained 1.1 percent gain during the same twelve months ending March 2026, and the total count of licensed premises together with betting shops continued its downward trajectory.
Breakdown of Revenue Streams
Figures released in September 2026 illustrate how remote channels captured the majority of the overall uplift, because operators in that space benefited from expanded digital engagement across multiple product types. Online casino games and slot offerings posted the strongest individual gains inside the remote category, whereas sports betting and other verticals showed steadier but less pronounced movement. The land-based side, by contrast, maintained stability through traditional venues even as fewer physical sites remained open across the country.
Those who track these statistics note that the 1.1 percent land-based advance occurred despite ongoing consolidation, which suggests existing locations sustained or slightly improved their per-site performance. Licensed premises declined in number, and betting shops followed the same pattern, reflecting longer-term adjustments that predate the most recent reporting cycle. Data indicates operators concentrated resources on fewer outlets while adapting to shifting consumer preferences that favor remote access.
Remote Sector Momentum
The remote segment's 6.9 percent advance to £8.3 billion stands out because it outpaced both the overall industry average and the land-based result by a clear margin. Within this channel, casino and slots products drove the bulk of incremental yield, supported by continuous platform enhancements and broader device compatibility that maintained player retention throughout the year. Observers note that these categories benefited from regulatory frameworks that already govern remote operations, allowing providers to scale offerings without major structural disruption.
Land-based venues, although growing modestly, faced constraints tied to physical infrastructure and reduced site counts. The combination of fewer premises and a smaller number of betting shops points to an industry that continues reallocating capacity toward digital formats. Annual report statistics from the Gambling Commission confirm the headline totals while also documenting these parallel trends in premises data.
Market Context and Adjustments
Year-on-year comparisons place the 4.4 percent total increase in perspective against earlier periods when remote growth already exceeded land-based results. The exclusion of lotteries produces a slightly higher percentage change because lottery yields typically follow more stable patterns that dilute headline volatility. When those figures receive removal, the remaining £13.2 billion underscores the core commercial segments' performance during the twelve months under review.
Operators across both channels navigated teh same macroeconomic environment, yet remote platforms demonstrated greater flexibility in responding to demand fluctuations. Land-based locations, operating under tighter geographic and licensing limits, recorded slower but consistent progress even as the number of active sites contracted. Those who monitor licensing records observe that this contraction aligns with prior years rather than representing an abrupt shift tied solely to the 2025-2026 results.
Implications for Licensed Operators
The divergence between remote expansion and land-based restraint carries direct consequences for how operators allocate capital and plan future deployments. Companies with strong digital portfolios captured disproportionate shares of the £8.3 billion remote total, while traditional venues focused on operational efficiency at remaining sites to achieve their 1.1 percent gain. The continued reduction in betting shops and other premises suggests further rationalization may occur before the next reporting cycle concludes.
Statistics compiled for the financial year ending March 2026 provide a clear snapshot of these dynamics, and the Gambling Commission report supplies the underlying datasets that support each percentage and absolute figure. Integration of these numbers into broader industry tracking allows stakeholders to compare performance across product lines without conflating lottery contributions with commercial gaming activity.
Conclusion
The April 2025 to March 2026 period closed with Great Britain's gambling sector posting £17.5 billion in gross gambling yield, driven chiefly by remote growth of 6.9 percent to £8.3 billion while land-based activity rose 1.1 percent amid ongoing declines in physical premises. Excluding lotteries yields £13.2 billion and a 4.7 percent increase, confirming the underlying commercial segments' contribution. These outcomes reflect established patterns of channel shift that persisted through the latest full financial year, with data now available for further analysis by regulators and participants alike.